SIP vs Lump Sum: Which Investment Approach Is Right for You
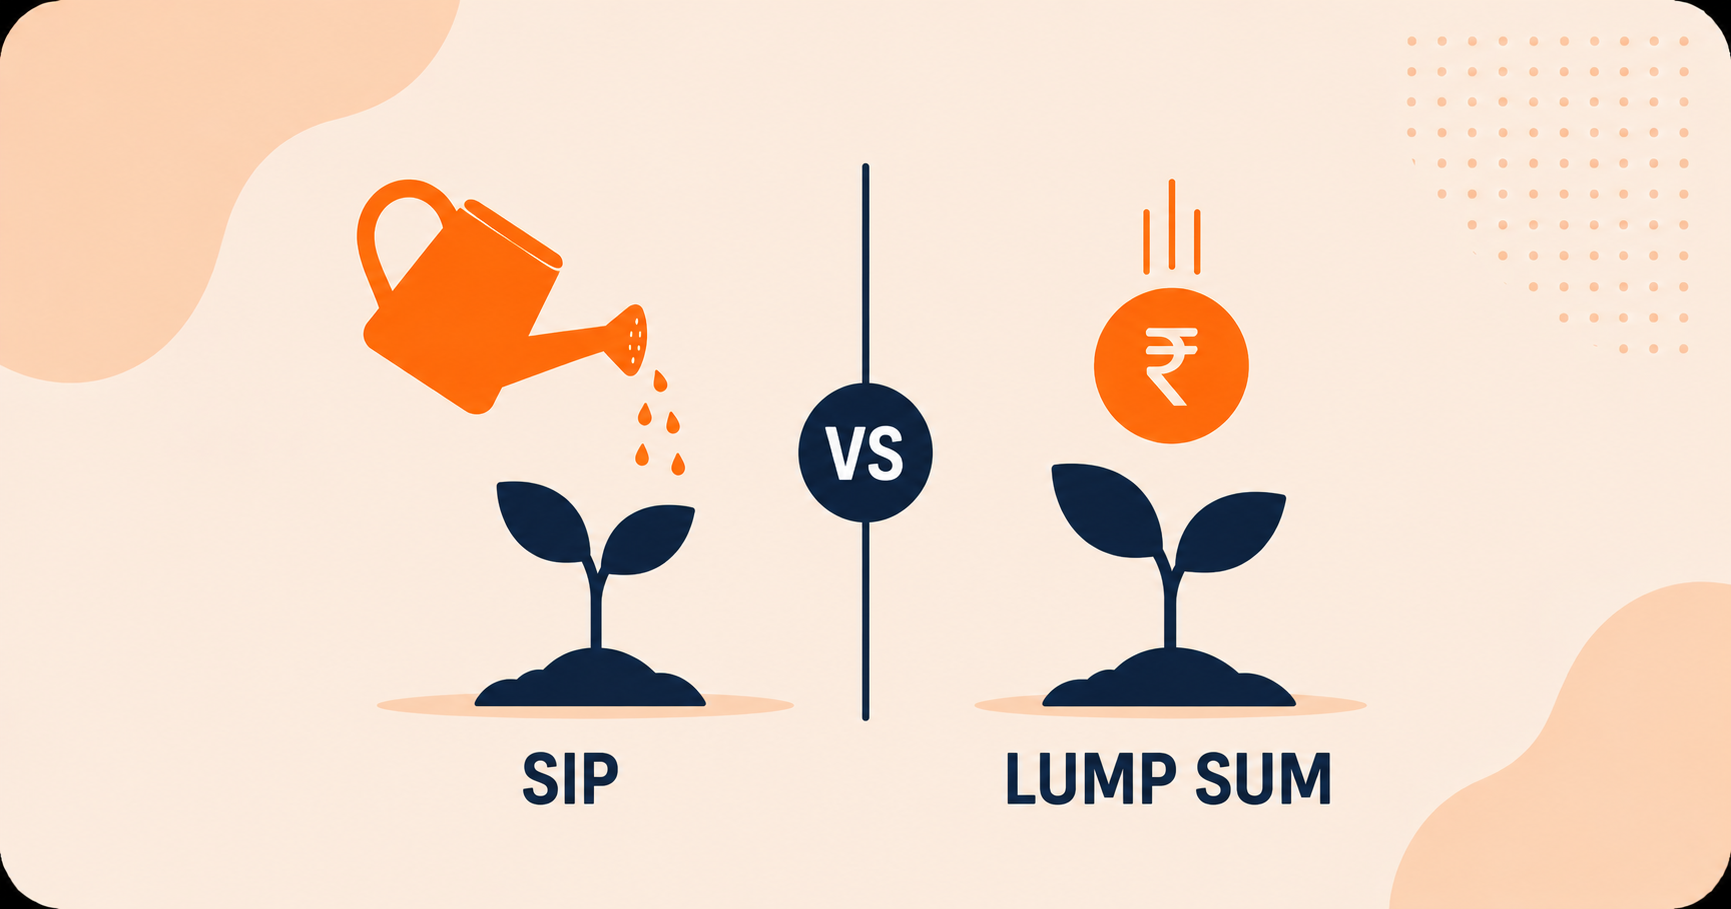
The SIP-vs-lump-sum debate gets treated like a permanent rivalry, but the honest answer is that each approach fits a different situation, and most people will use both at different points in their financial life.
What a SIP actually does for you
A Systematic Investment Plan invests a fixed amount regularly, regardless of whether the market is up or down. Its real value isn't some mathematical edge over lump sum investing — it's discipline and rupee-cost averaging: you naturally buy more units when prices are low and fewer when they're high, without having to time anything yourself. For most people building wealth from regular income, this is the more realistic, sustainable approach.
When a lump sum makes more sense
If you've received a bonus, an inheritance, or matured an investment and suddenly have a large amount to deploy, waiting to drip it in via SIP over months often means leaving that money sitting idle or in a low-return instrument in the meantime. In that situation, investing it as a lump sum — possibly staggered over a few weeks or months to reduce timing risk, rather than in one go — is usually more sensible than artificially stretching it into a SIP schedule.
The real question isn't which is "better"
Comparative studies on SIP versus lump sum performance depend heavily on which market period you pick, which makes the debate somewhat beside the point for individual decisions. The more useful question is: how did you come by this money, and what's realistic for your cash flow? Regular income naturally suits SIP; a windfall naturally suits some form of lump sum deployment.
Both require the same thing underneath: asset allocation
Neither approach matters as much as getting your underlying asset allocation right for your goals and risk tolerance. A well-timed lump sum into the wrong asset mix, or a disciplined SIP into an inappropriate fund, both undermine the actual goal.
If you're not sure how a lump sum or your monthly SIP fits into your bigger financial picture, that's exactly the kind of question a Personal Finance Professional can help with — start with a free Financial Health Check to get matched with one whose expertise fits your situation.
Want to see where your own finances stand?
Start Your Free Health Check